What’s the Right Medicare Plan for Me?
Have your question answered on the Money Wisdom Question Series!
There is a lot to consider when choosing the right Medicare plan: How often do you visit the doctor? Do you have any chronic conditions? Do you take prescription drugs regularly? Answering these questions can help you pinpoint the type of coverage you need.
In this week’s Money Wisdom Question Series, join Jake Doser, CFP®, CPWA® as he goes deeper into demystifying key Medicare decisions, starting with the differences between Parts A, B, C, and D.
Parts A & B: Original Medicare
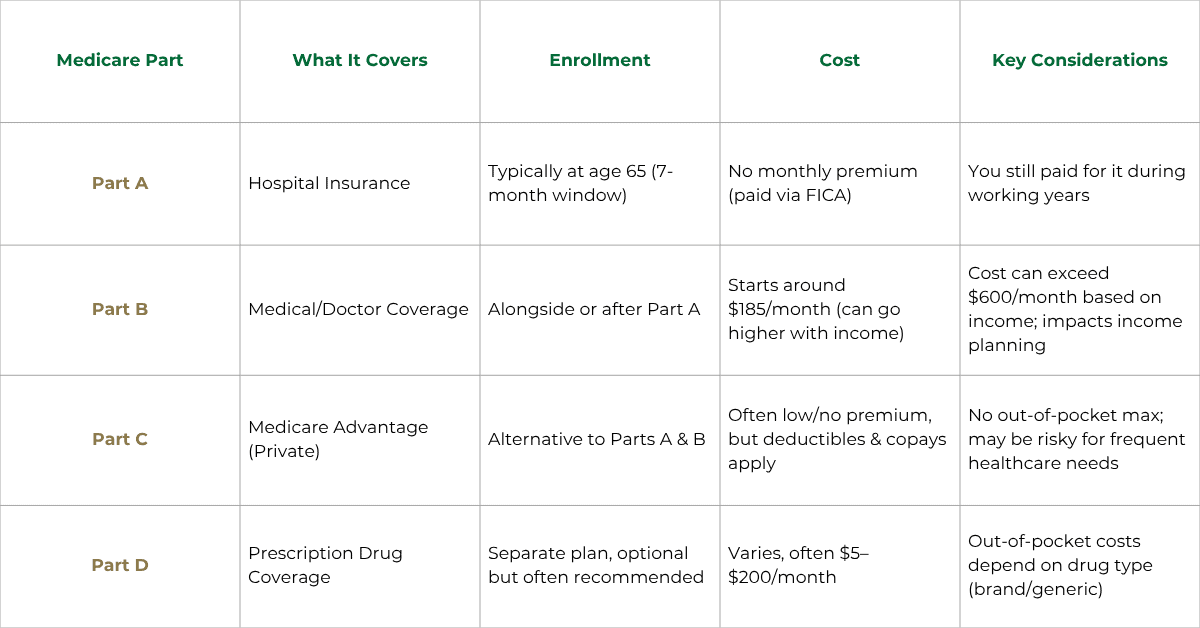
Medicare Part A is the initial coverage most people enroll in when they turn 65. You have a seven-month Initial Enrollment Period (IEP) that begins three months before your 65th birthday, includes the month you turn 65, and continues for three months afterward. While there is technically no monthly premium for Part A, you’ve been paying for this coverage throughout your working years via FICA taxes.
Next is Medicare Part B, which, when combined with Part A, is referred to as Original Medicare. Unlike Part A, Part B requires a monthly premium, currently starting at $185 per month. However, if your income exceeds certain thresholds, this premium can increase significantly. That’s why it’s important to include Medicare costs in your overall income planning strategy.
Part C: Medicare Advantage
You also have the option to sign up for Medicare Part C, instead of Parts A & B. Known as Medicare Advantage, these plans often have little to no monthly premium, but they usually include deductibles and copayments.
Additionally, many Medicare Advantage plans do not have a cap on out-of-pocket expenses, so costs can add up quickly. If you have frequent doctor visits or upcoming surgeries, this may not be the best option for you.
Part D: Prescription Drug Coverage
Finally, Medicare Part D is available for prescription drug coverage. Costs for Part D often range from $5 to $200 per month, depending on the medications you need and whether they are brand name or generic. You may also have out-of-pocket expenses based on your prescriptions.
Discuss Your Options with an Agent
It’s important to carefully consider which Medicare plan makes the most financial sense within the context of your overall retirement plan. Working with an independent Medicare agent who understands your options and can provide unbiased advice is crucial. Independent agents have access to a wider range of plans and can help you find the best fit for your needs.
Download Now
10-Point Retirement Checklist
Here’s a checklist of our most important things you can do, to help you retire strong.
Information presented here is considered current as of the created date. Over time, some information presented may become stale. We recommend you consult with your Financial Professional before making any changes based on information contained here.
Johnson Brunetti is a marketing name for the businesses of JB Capital and JN Financial.
Investment Advisory Services offered through JB Capital, LLC. Insurance Products offered through JN Financial, LLC.
The guarantees provided by any type of insurance contract are based on the claims-paying ability of the insurance company.
Related Resources
-
Do I Need Life Insurance in Retirement?
Around 52% of Americans own some type of life insurance policy. But once you retire, some of your biggest financial obligations may be behind you. When you reach this point, you may wonder whether… -
How Will Social Security Be Funded in the Future?
Without congressional action, current projections indicate Social Security will pay only 78% of benefits starting in late 2032. This funding gap highlights our growing disparity between workers pa… -
How Should I Withdraw From My 401(k) Before I’m Forced To?
When turning your investments into retirement income, it’s important to consider the impact of taxes. Once required minimum distributions (RMDs) begin, you’ll generally have to withdraw money from… -
I’m 10 Years Away from Retirement – What Should I Be Doing?
If you’re about 10 years from retirement, now is the time to start building a plan for the life you want to live. Think about how you want to spend your time in retirement and the lifestyle you en… -
What’s the Difference Between a Roth IRA and a Traditional IRA?
An individual retirement arrangement (IRA) is a powerful investment vehicle. These accounts help you save for retirement on your own, without an employer. But the tax benefits vary significantly d… -
Podcast Episode 463: 4 Health Insurance Options for Early Retirees
Prefer to watch? Click here to watch and listen on YouTube. According to a 2026 Retirement Confidence Survey, 3 in 5 retirees report retiring earlier than age 65. If you retire early, you’ll ne… -
Do I Need to Sign Up for Medicare at 65 If I’m Still Working?
Turning 65 is a major Medicare milestone. Signing up on time is key to avoiding gaps in coverage and a monthly Part B late enrollment penalty. However, if you’re still working, you may be able to … -
Will Social Security Be Around When I Retire?
The trust fund that pays Social Security retirement benefits may run out three months earlier than expected. This new information raises two important questions: How long will Social Security last… -
How Would Part-Time Work Affect My Retirement Plan?
In 2024, 38% of employed people aged 65 or older worked part-time. Many retirees choose to stay at least partially in the workforce to supplement their income or maintain a sense of routine. Howev… -
Are My Finances on Track for the Rest of the Year?
Have you made any progress with the financial goals you set back in January? Now that we’ve reached the halfway point of the year, it’s a great opportunity to see where your finances stand. Joi…
-
Richard S.Richard S. is a client of Johnson Brunetti and received no compensation for his statement.
“We have been extremely happy with our advisor and the services offered. We previously had accounts with another advisor. We had no issues, but chose to consolidate everything with Johnson Brunetti. We made a great decision with that.”
Testimonials received in response to Johnson Brunetti survey conducted in 2024 and in 2026. Please click each respective year for a description of the respective survey and a summary of the survey results.
-
John & Laura U.John & Laura U. are clients of Johnson Brunetti and received no compensation for their statement.
-
Joe D.Joe D. is a client of Johnson Brunetti and received no compensation for his statement.
“Your model is working well, continue to keep your focus on your clients. The podcasts are an effective way of communicating information and real life stories. Your business is supporting your clients’ many different real life stories.”
Testimonials received in response to Johnson Brunetti survey conducted in 2024 and in 2026. Please click each respective year for a description of the respective survey and a summary of the survey results.
-
Jackie L.Jackie L. is a client of Johnson Brunetti and received no compensation for her statement.
“I love how everyone in the company makes us feel. Like we are one big happy family. I wouldn’t change anything!”
Testimonials received in response to Johnson Brunetti survey conducted in 2024 and in 2026. Please click each respective year for a description of the respective survey and a summary of the survey results.
-
Donald & Donna K.Donald & Donna K. are clients of Johnson Brunetti and received no compensation for their statement.
“It’s been one of the best things my wife and I have ever done. The clarity, support, and professionalism have made a real difference for us.”
Testimonials received in response to Johnson Brunetti survey conducted in 2024 and in 2026. Please click each respective year for a description of the respective survey and a summary of the survey results.
-
Annette L.Annette L. is a client of Johnson Brunetti and received no compensation for her statement.