Created: January 29, 2023
Modified: May 14, 2024

Episode 84: How Can I Prepare for IRS Changes in 2023?

Have your question answered on the Money Wisdom Question Series!

Planning for IRS changes in 2023

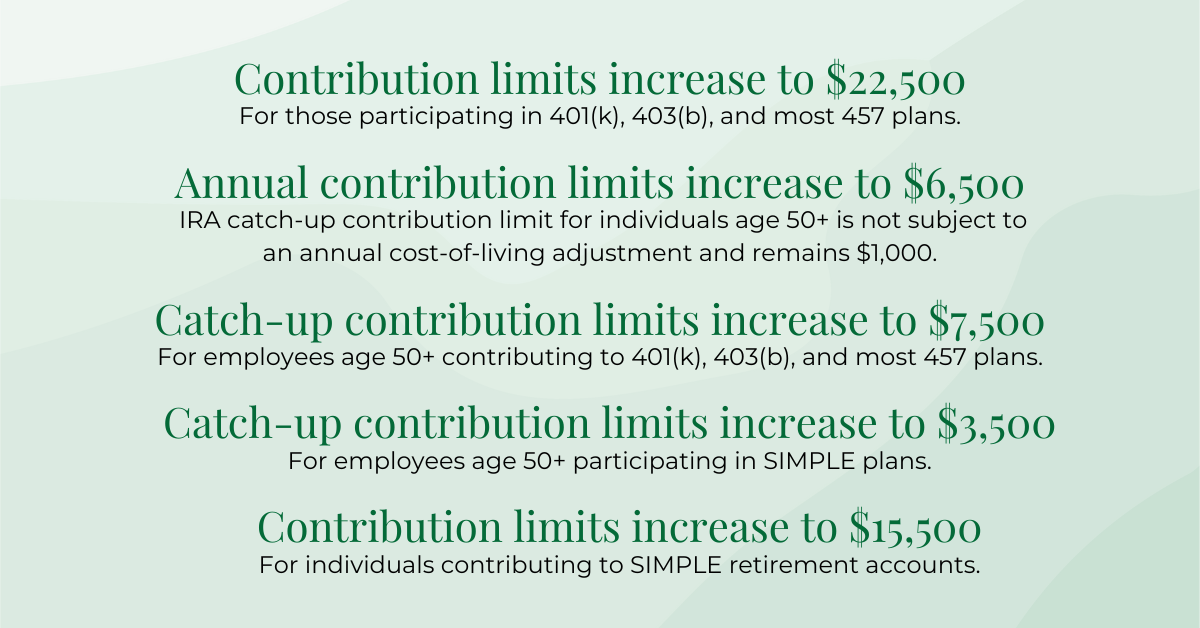
There are relevant and very important changes for those focusing on retirement planning to know. Due to inflation, the IRS has increased the contribution limits in retirement plans such as 401(K)s, 403(B)s, 457s, and some others, from $20,500 to $22,500 for everyone. If you’re over 50, they’ve increased it from $6,500 to $7,500. If you are over 50 and have the income, you can set aside as much as $30,000 tax-free into your 401(k) plan. That’s a big advantage that inflation has given us with the IRS tax code changes.
Adjusted Tax Brackets

Another change is adjusted brackets. The tax rates haven’t changed, but the brackets have broadened. Visually, you can imagine the buckets that hold certain amounts of money have gotten bigger. So, we all paid the same taxes on the same amounts of money as we go up through the income scale. Everybody pays 10 – 12% on the same amounts of money. The IRS has made those buckets about 7% larger.

In essence, all of us in 2023 will end up paying less taxes on our money. That doesn’t mean tax rates have changed. It means the brackets have gotten a little bit bigger, holding a little bit more money, which lowers our tax bill. If you’re saving into a retirement plan at work and you’re not able to meet the maximum amount of contribution limits, even making a small change that fits your goal and your desired retirement plan may push you into a lower tax bracket with how 401(k) deductions work on your W-2. That is a huge advantage someone can take to maximize their retirement plan and to minimize their taxes. It’s always a win-win when you get to pay less taxes and have more fun in retirement, which really is the goal.

If You’re Already Retired

For those that are already in retirement and are past the saving cycle, be aware that larger tax brackets can allow us to plan for an event, or something expensive, coming up in a few years. Taking the money out to keep ourselves at a lower tax bracket is one way we can maximize tax efficiency in our retirement plan because of these changes.

Roth Conversions

Another exciting way we can maximize tax efficiency is by doing Roth conversions for future planning. This gives us a little more room in the bucket to keep a lower tax rate on the amount that we convert into a Roth. Those are just a couple of ways that the tax changes in 2023 can impact us.

Find A Financial Professional

I just want to encourage you, if you don’t have a financial planner, to find one. It makes all the difference in retirement. Some retirement rules, like these IRS rules, can seem simple on their own, however, keep in mind the two we touched on, and how they interconnect and interrelate to one another is what makes them much more complex. Every person’s plan is different and unique to them. Figuring out how to take all these moving parts and put them together so that they work for you ensures that you can have your best retirement.

Information presented here is considered current as of the created date. Over time, some information presented may become stale. We recommend you consult with your Financial Professional before making any changes based on information contained here.

Johnson Brunetti is a marketing name for the businesses of JB Capital and JN Financial.
Investment Advisory Services offered through JB Capital, LLC. Insurance Products offered through JN Financial, LLC.
The guarantees provided by any type of insurance contract are based on the claims-paying ability of the insurance company.

Resources by Topic

Subscribe to Our YouTube Channel

Share

Related Resources

  • What Are the 4 Parts of Medicare?

    While most Medicare recipients feel confident about their coverage options, only 13% can correctly identify the four main parts. If you’re approaching Medicare eligibility, you may feel overwhelme…
  • Should I Stay in My Home or Rent in Retirement?

    Most retirees plan to remain homeowners, but it’s worth considering if that’s the right move for you. Whether you should stay in your home or rent in retirement depends on your financial situation…
  • Podcast Episode 472: 3 Year-End Charitable Giving Strategies

    Prefer to watch? Click here to watch and listen on YouTube. Supporting causes close to your heart and reducing your tax burden don’t have to be mutually exclusive. In fact, with the right strat…
  • What Tax Moves Should I Consider Before the End of the Year?

    According to a recent study, 46% of Americans say tax season is the most stressful financial time of the year. The good news is that there are several proactive steps you can take before year-end …
  • What’s the Best Way to Leave an Inheritance?

    Leaving an inheritance is about more than transferring wealth. With thoughtful planning, you can help maximize the value of what you leave behind and simplify the process for your loved ones. I…
  • What Are the Best Types of Accounts for Investing?

    Different investment accounts offer different advantages. From tax benefits and contribution limits to withdrawal rules, each account serves a unique purpose. Understanding how these accounts work…
  • I’m Turning 65, Why Do I Need to Stop My HSA Contributions?

    If you’re nearing your mid-60s and actively contribute to a health savings account (HSA), you’ve likely used it to cover qualified medical costs. However, as you get closer to enrolling in Medicar…
  • How Can I Enjoy My Retirement Savings Without Fear of Overspending?

    The fear of running out of money keeps many retirees from truly enjoying their hard-earned savings without worry. After decades of nurturing your nest egg, the thought of seeing your progress slip…
  • Do I Need Life Insurance in Retirement?

    Around 52% of Americans own some type of life insurance policy. But once you retire, some of your biggest financial obligations may be behind you. When you reach this point, you may wonder whether…
  • How Will Social Security Be Funded in the Future?

    Without congressional action, current projections indicate Social Security will pay only 78% of benefits starting in late 2032. This funding gap highlights our growing disparity between workers pa…
    Back to top
    • Richard S.
      Richard S. is a client of Johnson Brunetti and received no compensation for his statement.

      “We have been extremely happy with our advisor and the services offered. We previously had accounts with another advisor. We had no issues, but chose to consolidate everything with Johnson Brunetti. We made a great decision with that.”

      Testimonials received in response to Johnson Brunetti survey conducted in 2024 and in 2026.  Please click each respective year for a description of the respective survey and a summary of the survey results.

    • John & Laura U.
      John & Laura U. are clients of Johnson Brunetti and received no compensation for their statement.

      “We have had nothing but a positive experience.”

      Testimonials received in response to Johnson Brunetti survey conducted in 2024 and in 2026.  Please click each respective year for a description of the respective survey and a summary of the survey results.

    • Joe D.
      Joe D. is a client of Johnson Brunetti and received no compensation for his statement.

      “Your model is working well, continue to keep your focus on your clients. The podcasts are an effective way of communicating information and real life stories. Your business is supporting your clients’ many different real life stories.”

      Testimonials received in response to Johnson Brunetti survey conducted in 2024 and in 2026.  Please click each respective year for a description of the respective survey and a summary of the survey results.

    • Jackie L.
      Jackie L. is a client of Johnson Brunetti and received no compensation for her statement.

      “I love how everyone in the company makes us feel. Like we are one big happy family. I wouldn’t change anything!”

      Testimonials received in response to Johnson Brunetti survey conducted in 2024 and in 2026.  Please click each respective year for a description of the respective survey and a summary of the survey results.

    • Donald & Donna K.
      Donald & Donna K. are clients of Johnson Brunetti and received no compensation for their statement.

      “It’s been one of the best things my wife and I have ever done. The clarity, support, and professionalism have made a real difference for us.”

      Testimonials received in response to Johnson Brunetti survey conducted in 2024 and in 2026.  Please click each respective year for a description of the respective survey and a summary of the survey results.

    • Annette L.
      Annette L. is a client of Johnson Brunetti and received no compensation for her statement.

      “Your services are excellent!”

      Testimonials received in response to Johnson Brunetti survey conducted in 2024 and in 2026.  Please click each respective year for a description of the respective survey and a summary of the survey results.

      Our Locations
      Johnson Brunetti
      Welcome to Our New Website!
      Everything was designed with you in mind, making our retirement planning resources more easily accessible to you.
      Check out your new resource center, where everything can be organized by article type or topic
      Are you ready to speak with a financial advisor?
      Skip to content