Created: September 3, 2021
Modified: January 3, 2025

Episode 15: Should I Buy Long-Term Care Insurance?

Have your question answered on the Money Wisdom Question Series!

Thank you for joining us for Episode 15 of our Money Wisdom Question Series, where we film answers to common financial and retirement investment questions. Today’s question is “Should I buy long-term care insurance?” It’s a big subject that always comes up and people have a lot of concerns about it.

What is Long-Term Care Insurance?

Long-term care insurance covers you if you need care in your home or in a nursing home. Specifically, it includes a variety of services aimed at helping individuals accomplish the Activities of Daily Living (ADLs). There are varying levels of long-term care dependent upon each person’s assistance level needed.

The Cost of Long-Term Care Insurance

The cost of long-term care insurance does continue to get more expensive and very often, people do say this is a big factor for them. Below is the 2019 Price Index for the average annual premium long-term care insurance. (statistics provided by the American Association for Long-Term Care Insurance)
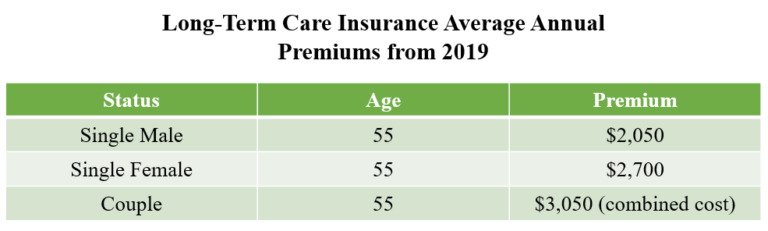
People will say, “I don’t want to pay insurance for a nursing home.”, but that’s not the reason for purchasing it. It’s to protect your money so that you don’t spend everything on care. If you pass away and didn’t purchase long-term care insurance and ended up having all those medical costs, now there’s no money left for a widow, family, or any other reason that you were saving that money for. It’s expensive because what it insures is very expensive.

What is Your Plan for Long-Term Care?

You don’t necessarily need to buy long-term care insurance, but you do need to have a conversation about what your plan is if you or your spouse gets sick. Your plan could be long-term care insurance. It could be looking at an estate plan or shifting assets out of your name. There are pros and cons to each one of these scenarios. When you look at long-term care insurance, it is a product specifically designed to pay for that need.

Unfortunately, many of us have had grandparents that have been in healthcare facilities. We have had clients that have been in care facilities paying hundreds of thousands of dollars a year. It also depends on the state that you’re living in. For example, here in Connecticut, there is a very high cost of care. You can receive really good care, but it’s expensive.

Don’t Delay

I wouldn’t delay this conversation any longer. Like anything, get a number of different opinions on it. If someone is saying you really need to buy the insurance, think about what is best for you before making that big financial commitment. There are really great options available to you, but make sure to get multiple inputs on them. The most important thing is to have a plan.

Thanks for joining me and I hope you found this information helpful! If you enjoyed this topic and you want to hear more, you’ll love this Forbes article where Joel talks more about long-term care insurance.

P.P.S. Feel free to submit questions here for a chance to have them answered!

Download Now

Estate Planning Simplified

Estate planning is a large component of retirement planning, ensuring your assets are distributed according to your final wishes. Creating an estate plan allows greater control, privacy and security of your legacy.

Information presented here is considered current as of the created date. Over time, some information presented may become stale. We recommend you consult with your Financial Professional before making any changes based on information contained here.

Johnson Brunetti is a marketing name for the businesses of JB Capital and JN Financial.
Investment Advisory Services offered through JB Capital, LLC. Insurance Products offered through JN Financial, LLC.
The guarantees provided by any type of insurance contract are based on the claims-paying ability of the insurance company.

Resources by Topic

Estate Planning Simplified


Subscribe to Our YouTube Channel

Share

Related Resources

  • I’m Turning 65, Why Do I Need to Stop My HSA Contributions?

    If you’re nearing your mid-60s and actively contribute to a health savings account (HSA), you’ve likely used it to cover qualified medical costs. However, as you get closer to enrolling in Medicar…
  • How Can I Enjoy My Retirement Savings Without Fear of Overspending?

    The fear of running out of money keeps many retirees from truly enjoying their hard-earned savings without worry. After decades of nurturing your nest egg, the thought of seeing your progress slip…
  • Do I Need Life Insurance in Retirement?

    Around 52% of Americans own some type of life insurance policy. But once you retire, some of your biggest financial obligations may be behind you. When you reach this point, you may wonder whether…
  • How Will Social Security Be Funded in the Future?

    Without congressional action, current projections indicate Social Security will pay only 78% of benefits starting in late 2032. This funding gap highlights our growing disparity between workers pa…
  • Podcast Episode 466: Is Long-Term Care Insurance Worth It​?

    Prefer to watch? Click here to watch or listen on YouTube. Long-term care is one of the biggest financial blind spots in retirement planning. About 58% of people falsely believe Medicare will c…
  • How Should I Withdraw From My 401(k) Before I’m Forced To?

    When turning your investments into retirement income, it’s important to consider the impact of taxes. Once required minimum distributions (RMDs) begin, you’ll generally have to withdraw money from…
  • I’m 10 Years Away from Retirement – What Should I Be Doing?

    If you’re about 10 years from retirement, now is the time to start building a plan for the life you want to live. Think about how you want to spend your time in retirement and the lifestyle you en…
  • What’s the Difference Between a Roth IRA and a Traditional IRA?

    An individual retirement arrangement (IRA) is a powerful investment vehicle. These accounts help you save for retirement on your own, without an employer. But the tax benefits vary significantly d…
  • Do I Need to Sign Up for Medicare at 65 If I’m Still Working?

    Turning 65 is a major Medicare milestone. Signing up on time is key to avoiding gaps in coverage and a monthly Part B late enrollment penalty. However, if you’re still working, you may be able to …
  • Will Social Security Be Around When I Retire?

    The trust fund that pays Social Security retirement benefits may run out three months earlier than expected. This new information raises two important questions: How long will Social Security last…
    Back to top
    • Richard S.
      Richard S. is a client of Johnson Brunetti and received no compensation for his statement.

      “We have been extremely happy with our advisor and the services offered. We previously had accounts with another advisor. We had no issues, but chose to consolidate everything with Johnson Brunetti. We made a great decision with that.”

      Testimonials received in response to Johnson Brunetti survey conducted in 2024 and in 2026.  Please click each respective year for a description of the respective survey and a summary of the survey results.

    • John & Laura U.
      John & Laura U. are clients of Johnson Brunetti and received no compensation for their statement.

      “We have had nothing but a positive experience.”

      Testimonials received in response to Johnson Brunetti survey conducted in 2024 and in 2026.  Please click each respective year for a description of the respective survey and a summary of the survey results.

    • Joe D.
      Joe D. is a client of Johnson Brunetti and received no compensation for his statement.

      “Your model is working well, continue to keep your focus on your clients. The podcasts are an effective way of communicating information and real life stories. Your business is supporting your clients’ many different real life stories.”

      Testimonials received in response to Johnson Brunetti survey conducted in 2024 and in 2026.  Please click each respective year for a description of the respective survey and a summary of the survey results.

    • Jackie L.
      Jackie L. is a client of Johnson Brunetti and received no compensation for her statement.

      “I love how everyone in the company makes us feel. Like we are one big happy family. I wouldn’t change anything!”

      Testimonials received in response to Johnson Brunetti survey conducted in 2024 and in 2026.  Please click each respective year for a description of the respective survey and a summary of the survey results.

    • Donald & Donna K.
      Donald & Donna K. are clients of Johnson Brunetti and received no compensation for their statement.

      “It’s been one of the best things my wife and I have ever done. The clarity, support, and professionalism have made a real difference for us.”

      Testimonials received in response to Johnson Brunetti survey conducted in 2024 and in 2026.  Please click each respective year for a description of the respective survey and a summary of the survey results.

    • Annette L.
      Annette L. is a client of Johnson Brunetti and received no compensation for her statement.

      “Your services are excellent!”

      Testimonials received in response to Johnson Brunetti survey conducted in 2024 and in 2026.  Please click each respective year for a description of the respective survey and a summary of the survey results.

      Our Locations
      Johnson Brunetti
      Welcome to Our New Website!
      Everything was designed with you in mind, making our retirement planning resources more easily accessible to you.
      Check out your new resource center, where everything can be organized by article type or topic
      Are you ready to speak with a financial advisor?
      Skip to content